
In the landscape of personal finance, few subjects are as volatile—or as essential—as the conversation between romantic partners regarding money. While many couples view financial disagreements as an indicator of fundamental incompatibility, experts suggest that the conflict itself is not the problem. Instead, the issue lies in the "dance" of the relationship: the repetitive, often unconscious interaction patterns that define how we communicate about our bank accounts, debts, and future goals.
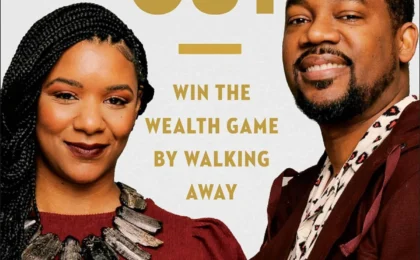
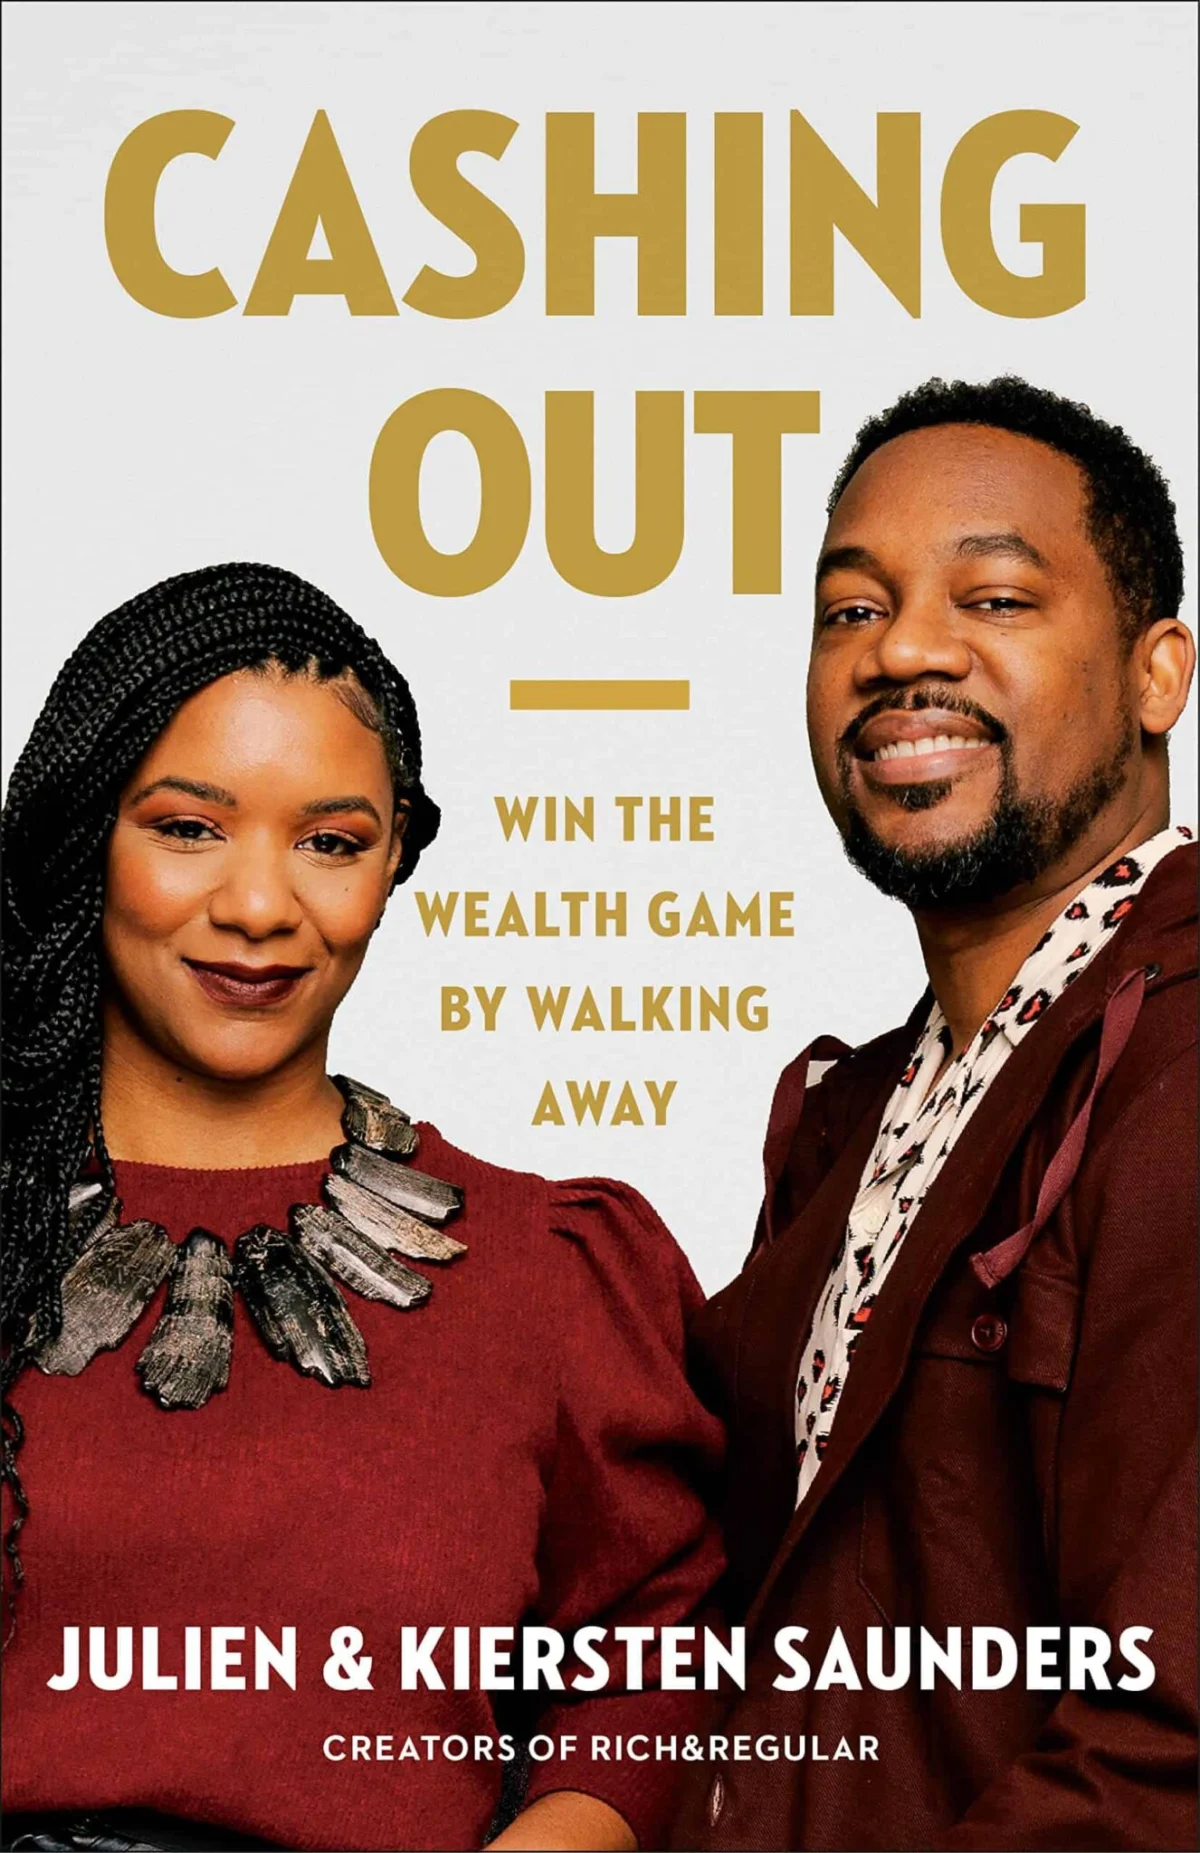
This perspective is central to the new book Cashing Out: Win the Wealth Game by Walking Away by Julien and Kiersten Saunders, the visionaries behind the influential rich & REGULAR blog. By adapting the theories of clinical psychologist Dr. Sue Johnson—who pioneered emotionally focused therapy—the Saunders offer a roadmap for couples looking to replace blame and anxiety with emotional attunement.
The Core Concept: Financial Choreography
Dr. Sue Johnson posits that when couples clash, they are participating in a metaphorical dance. One partner initiates a move, and the other responds, creating a cycle that often traps them in a loop of frustration. The Saunders argue that to move past financial gridlock, couples must stop viewing their partner as an adversary and instead view the "dance" as the challenge.
Emotional attunement is the key to mastering this choreography. It requires both partners to hear the same "music"—the underlying emotional needs—rather than just reacting to the surface-level noise of a budget dispute. If one partner is "grooving to Barry White" while the other is "swinging to Barry Manilow," conflict is inevitable. Without attunement, many couples end up in a "silent disco," where both are dancing to their own rhythm, unaware of why their partner is reacting the way they are.
Chronology of a Financial Conflict
Financial intimacy is not a static state; it is an evolution. For most couples, the journey begins with avoidance, moves through cycles of miscommunication, and—if handled with maturity—culminates in a collaborative financial partnership.
Phase 1: The Silent Disco
The initial stage of financial struggle is characterized by silence. Couples often avoid deep conversations about money, fearing that bringing up the subject will trigger an argument or reveal uncomfortable truths about spending habits. During this phase, resentment builds beneath the surface.
Phase 2: The "Name-Calling" Cycle
As tensions rise, the "saver vs. spender" narrative emerges. This is often the point where couples seek professional intervention. The "saver" typically frames themselves as the responsible, rational party, while casting the "spender" as the reckless, impulsive villain. This binary thinking is, according to the Saunders, a major pitfall.
Phase 3: The Nagging Loop
Once a couple establishes these roles, the nagging begins. The "saver" monitors the "spender," creating a dynamic of surveillance that mimics a parent-child relationship. This erodes trust and ensures that every interaction feels like a confrontation.
Phase 4: Attunement and Synthesis
The final stage is the arrival at a state of harmony. This is where couples drop the labels, acknowledge their mutual desire for security or pleasure, and begin to plan their financial future as a team.
Supporting Data: Why "Savers" and "Spenders" are Myths
One of the most profound revelations in Cashing Out is the dismantling of the "saver/spender" dichotomy. The Saunders suggest that these are not fixed personality traits but rather fluid concepts defined by a single variable: the time horizon.
- Spenders: Individuals who prioritize immediate gratification or current needs.
- Savers: Individuals who prioritize future consumption.
The difference is not moral, but chronological. If a couple saves for an entire year to pay cash for a vehicle, they are acting as "savers" during the accumulation phase and "spenders" during the purchase phase. By shifting the paradigm from "good versus bad" to "now versus later," couples can eliminate the moral superiority often associated with saving. This objective view allows for a non-judgmental analysis of money decisions, turning the focus toward the "feeling" being chased. Whether it is security, spontaneity, or comfort, once the underlying emotional goal is identified, the conversation shifts from conflict to creative problem-solving.
The Pitfalls of Nagging and Blaming
Nagging is identified as "conversational quicksand." It is a persistent, low-level assault that pushes the recipient into a defensive posture. In a relationship, constant unsolicited advice about money acts as a wedge, making the partner feel that the real "beef" is not about the bank account, but about their worth as a person.
Addressing the Debt Stigma
Debt is another area where "blaming" frequently ruins intimacy. The person carrying the debt often harbors deep shame, while the debt-free partner may feel trapped by a sense of obligation. This creates a toxic atmosphere.
The Saunders suggest that for couples to move forward, both must "let go." The debtor must release the fantasy of being "rescued," and the creditor must release their judgment. Whether a couple chooses to pay off debt jointly or maintain separate financial responsibilities, the success of the strategy depends on it being a coordinated, intentional effort rather than a point of contention.
Official Guidance: The "Tell Me More" Technique
To navigate these charged waters, the Saunders recommend a simple but powerful linguistic tool: the phrase "tell me more."
This phrase serves as a signal that the listener is seeking context rather than judgment. It acts as an invitation for the partner to share their perspective without fear of a immediate counter-attack. However, the authors provide a critical caveat: this tool is not a magic wand. In moments of extreme emotional distress—where a partner feels threatened or overwhelmed—"tell me more" can feel like an interrogation. In such cases, patience and the preservation of the "dance floor" (the relationship) must take precedence over the immediate resolution of the financial issue.
Implications for Modern Relationships
The implications of the Saunders’ approach extend beyond personal finance. By applying emotional intelligence to money, couples can improve their communication across all facets of their lives.
- Reframing Requests: Replace accusatory statements with "I" statements. Instead of criticizing a partner’s spending, share your own goals and invite them to participate in the excitement of a shared future.
- Anticipation as a Tool: Use the excitement of future goals—like a planned vacation or a major purchase—as a psychological buffer against the discipline required for saving. Optimism is a far more effective motivator than willpower.
- The "Release Valve" Method: Whenever a conversation about saving becomes high-pressure, pivot to discussing the "why." Focusing on the future reward acts as a release valve for the tension created by present-day sacrifices.
Achieving Harmony
The goal of financial management in a relationship is not merely to balance the books, but to achieve a state of harmony. In this state, both partners feel empowered to express their needs while contributing to a collective vision. By recognizing that the dance—the pattern of interaction—is the true challenge, couples can break free from the cycle of blame.
As Julien and Kiersten Saunders demonstrate, the journey to financial wellness is rarely about the math; it is about the humanity. When you remove the labels of "good" and "bad" and replace them with "now" and "later," you stop fighting each other and start moving to the same beat. The result is not just a healthier bank account, but a stronger, more resilient partnership.