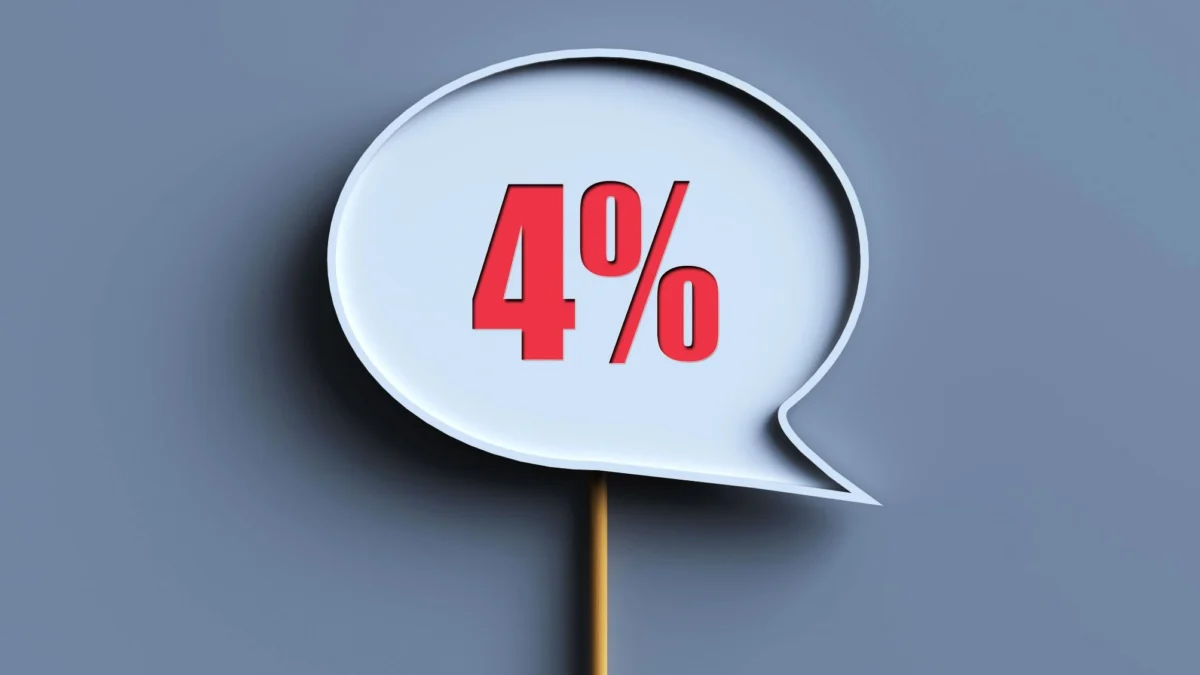
One of the most daunting challenges facing retirees is the "sustainability paradox": how to effectively decumulate a lifetime of savings without the looming fear of running out of money before the end of life. For decades, the financial industry has relied on the "4% rule" as a shorthand solution. While it provides a convenient starting point for back-of-the-envelope calculations, relying on it as a definitive roadmap is a dangerous oversimplification.
True retirement security requires a dynamic, multifaceted strategy that accounts for the harsh realities of market volatility, inflation, tax law evolution, and the unpredictable nature of human longevity.
The 4% Rule: A Brief History and Its Limitations
The 4% rule originated from research by financial advisor William Bengen in the 1990s. The concept is straightforward: a retiree withdraws 4% of their initial portfolio balance in the first year of retirement, then adjusts that dollar amount annually to keep pace with inflation. Historically, this strategy demonstrated a high probability of success over a 30-year period, even during unfavorable market conditions.
However, the "rule" is a historical observation, not a law of physics. It assumes a specific asset allocation—typically a 50/50 or 60/40 mix of stocks and bonds—and operates on a static timeline. In today’s economic climate, characterized by longer life expectancies, shifting interest rate environments, and higher healthcare costs, the 4% rule is increasingly viewed as a baseline rather than a destination.
The Chronology of Retirement Risk
To understand why a static percentage is insufficient, one must look at the lifecycle of a retiree’s portfolio.
- The Early Years (The "Red Zone"): This is the most precarious phase of retirement. The impact of market performance in the first five to ten years of withdrawal is disproportionately higher than in later years. A severe market downturn here can permanently impair the portfolio’s ability to generate future income.
- The Mid-Retirement Phase: This period is often marked by a transition in spending. As health remains relatively stable, retirees often spend more on lifestyle and travel, but they must also prepare for the eventual "smile" of retirement spending, where expenses drop in middle age and potentially spike again in the final years due to long-term care needs.
- The Late-Stage Horizon: As the retiree enters their 80s and 90s, the focus shifts from growth to preservation and, ultimately, legacy. At this stage, required minimum distributions (RMDs) from tax-advantaged accounts may force income levels that exceed actual spending needs, necessitating sophisticated tax planning.
The Critical Variable: Sequence of Returns Risk
Perhaps the most significant threat to a retirement plan is "sequence of returns risk." This is the danger that the timing of market withdrawals will coincide with a period of poor performance.
Consider two hypothetical retirees, both starting with a $1 million portfolio and withdrawing $40,000 annually.
- Retiree A experiences a 10% market gain in their first year. Their portfolio grows, and they have more capital to weather future volatility.
- Retiree B retires just before a 20% market correction. Their portfolio drops to $800,000. After taking their $40,000 withdrawal, they are left with $760,000. To simply recover to their starting $1 million balance, they would need a gain of over 31%.
This illustrates why simply "averaging out" market returns in a spreadsheet is a fatal flaw in retirement planning. When you are withdrawing money, you are selling shares. If you are forced to sell those shares at depressed prices during a bear market, you destroy the "compounding engine" that the portfolio needs to sustain you for the next three decades.
Supporting Factors for a Resilient Strategy
A robust retirement income strategy must integrate several moving parts that go beyond simple percentages:
1. Investment Allocation and Longevity
Retiring at 60 requires a significantly different strategy than retiring at 70. A 35-year retirement horizon demands a level of growth-oriented assets to combat the erosive power of inflation, which can halve purchasing power over 20 years. Conversely, an overly aggressive portfolio may face catastrophic losses in the "Red Zone," leading to insolvency.
2. The Tax Landscape
Withdrawals are not "one-size-fits-all." They are heavily influenced by the tax treatment of the underlying accounts.
- Tax-Deferred (Traditional IRAs/401ks): Withdrawals are taxed as ordinary income, which can trigger higher Medicare premiums (IRMAA) and increase the taxability of Social Security benefits.
- Tax-Exempt (Roth IRAs): These offer a buffer against future tax rate hikes.
- Taxable Brokerage Accounts: These benefit from long-term capital gains rates but require careful tax-loss harvesting strategies.
3. The "Spending Floor" Concept
A successful plan often incorporates a "guardrail" strategy. Instead of a fixed inflation-adjusted withdrawal, a retiree might choose to reduce discretionary spending—such as travel or luxury purchases—during years when the market is down by more than 10%. This flexibility can significantly extend the life of a portfolio by preventing the "selling low" trap.
Expert Perspectives: The Role of Professional Guidance
While self-directed investing is popular, the complexity of retirement income planning often necessitates the oversight of a fiduciary financial advisor.
"The value of professional advice isn’t in predicting the market," says one industry expert. "It’s in building a disciplined system that prevents emotional decision-making during volatility."
Advisers provide an objective lens, helping to:
- Coordinate Social Security and Pensions: Determining the optimal age to claim Social Security is a massive lever in a retirement plan. Delaying benefits from 62 to 70 can result in a substantially higher monthly income, which acts as a "longevity hedge" for the remainder of the portfolio.
- Systematic Rebalancing: By automating the process of selling winners and buying losers, advisers ensure that the portfolio does not drift into a risk profile that is no longer appropriate for the retiree’s current age.
- Legacy Planning: Balancing the desire to leave a legacy with the need to ensure personal financial security requires advanced estate planning tools, such as trusts or gifting strategies, which are best managed in coordination with legal and tax professionals.
Implications for Future Planning
The shift from the "accumulation" phase of life to the "decumulation" phase is the most difficult transition an investor will ever make. It requires a psychological pivot from growth at all costs to risk management and cash-flow stability.
The 4% rule, while useful, is a blunt instrument in an era that demands precision. Modern retirement planning is about creating a "total income" approach. This includes:
- Establishing a cash reserve: Holding 1–2 years of living expenses in cash or cash equivalents to insulate the portfolio from short-term market crashes.
- Dynamic Spending: Adjusting the withdrawal rate based on annual portfolio performance.
- Tax-Aware Distributions: Strategically sequencing withdrawals to minimize lifetime tax liability.
- Health Care Integration: Factoring in the high probability of rising medical costs and potential long-term care needs.
Conclusion
The goal of a retirement plan should never be to simply maximize the amount withdrawn in the first year. Instead, it is to balance the need for a high quality of life today with the certainty of financial security for the rest of one’s life.
By moving away from static rules and toward a dynamic, personalized strategy, retirees can gain the confidence to spend their money—not just save it. Whether through the use of annuities, bond ladders, or total-return portfolios, the most successful plans are those that account for the unpredictable, allowing the retiree to focus on their life’s passions rather than the daily fluctuations of the stock market.
Disclaimer: This article is intended for general educational purposes and does not constitute individualized investment, tax, legal, or retirement advice. Readers are encouraged to consult with a qualified financial advisor to discuss their specific circumstances.