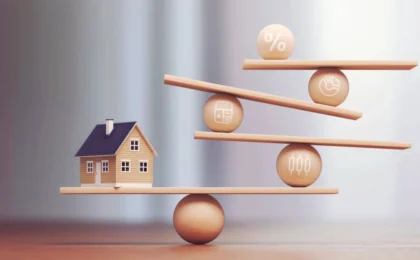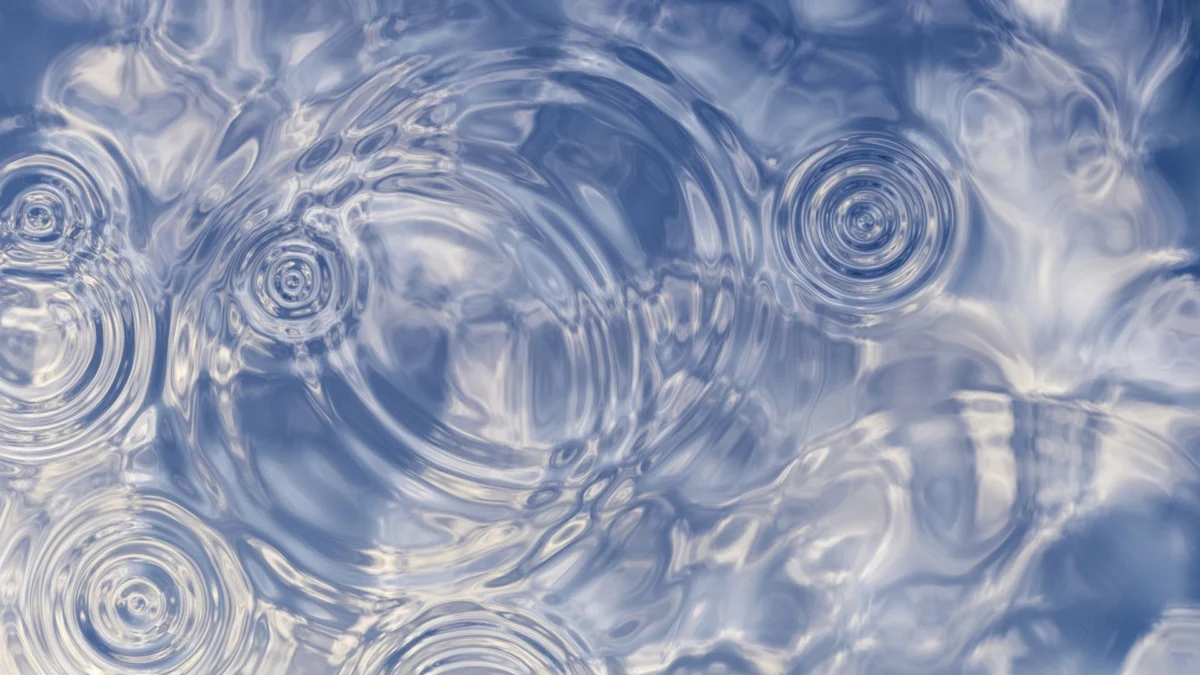
Retirement is rarely the linear, predictable journey that many envision during their working years. It is better understood as a vast, interconnected body of water—a "retirement lake"—where every financial decision acts as a stone tossed into the surface. Whether it is a routine withdrawal, a significant lifestyle purchase, a complex tax-hedging maneuver, or the timing of Social Security benefits, each choice generates ripples that radiate across a retiree’s entire financial horizon.
For financial advisors and their clients, the objective is not merely to manage individual events but to master the interplay of these ripples. A retirement plan that is resilient, flexible, and sustainable requires a holistic perspective that treats every decision as a catalyst for future outcomes. By understanding how these ripples interact, advisors can help clients build a roadmap that withstands market volatility and life’s inevitable surprises.
The Foundation: Lifetime Savings as the Reservoir
If retirement is a lake, then lifetime savings form its depth. This reservoir determines the total capacity for flexibility and security during one’s golden years. The choices made during the accumulation phase—prior to retirement—dictate the topography of the landscape that the retiree will eventually inhabit.
The "depth" of this reservoir is measured by a client’s ability to absorb shocks. When a major, unexpected expense occurs, a well-funded, diversified portfolio acts as a deep lake, absorbing the impact with minimal disruption to the overall water level. Conversely, a shallow reservoir—characterized by limited savings or poor asset allocation—means that even a small stone can cause significant, chaotic waves.
Key drivers of this reservoir include:
- Asset Allocation Strategy: The balance between growth-oriented equities and stability-focused fixed income.
- Contribution Rates: The consistency of funding tax-advantaged accounts like 401(k)s and IRAs.
- Risk Mitigation: The inclusion of insurance products or emergency funds that prevent the need to liquidate long-term investments during market downturns.
By strengthening this foundation early, advisors empower clients to make later-in-life decisions—such as supporting family or funding travel—without jeopardizing their long-term solvency.
Tax Planning: The Bridge Between Accumulation and Distribution
Once the reservoir is established, tax planning emerges as the critical bridge between the accumulation of wealth and its eventual distribution. This phase is where many retirees falter, as the tax consequences of a withdrawal strategy are often as significant as the market returns of the assets themselves.
Tax planning determines the efficiency of capital access. It dictates not only how much a client receives in their pocket but how long their total nest egg will last. Effective planning involves navigating:
- Bracket Management: Strategically realizing income to avoid being pushed into higher marginal tax tiers.
- Roth Conversions: Leveraging lower-income years to shift funds into tax-free growth vehicles.
- IRMAA Mitigation: Managing Modified Adjusted Gross Income (MAGI) to avoid the Income Related Monthly Adjustment Amount, which can significantly increase Medicare Part B and D premiums.
Consider the common, real-world scenario of a client purchasing a $50,000 vehicle at age 70. This is not just a spending event; it is a financial earthquake.
The Anatomy of a $50,000 Ripple
When a client decides to withdraw $50,000, they face a "liquidity shock." The advisor must determine the source of these funds, each carrying its own set of consequences:
- Tax-Deferred Withdrawals: Pulling from a traditional IRA may trigger a higher tax bracket, inflate the client’s MAGI, and trigger IRMAA surcharges. It may also consume "Roth conversion space," a missed opportunity to shift assets into a tax-advantaged status for future years.
- Taxable Account Liquidation: Selling assets in a brokerage account might trigger capital gains taxes, which depletes the principal and reduces the portfolio’s future income-producing potential.
- Cash Reserve Utilization: While seemingly the "safest" route, it lowers the client’s emergency liquidity, potentially forcing them to sell investments later if the market is down, creating a sequence-of-returns risk.
Beyond the immediate tax impact, such a purchase creates an 18-to-24-month spending ripple. This decision often necessitates a reduction in discretionary spending elsewhere to stabilize the portfolio, potentially affecting travel plans, gifts to grandchildren, or charitable contributions.
Lifetime Income Planning: The Synthesis of Strategy
Lifetime Income Planning (LIP) is the art of turning a collection of assets into a coordinated, predictable, and sustainable stream of cash. It is arguably the most difficult aspect of retirement, as it requires balancing three distinct categories of assets:
- Assets to "Lean On": Conservative, liquid holdings designed for immediate needs and emergencies.
- Assets to "Live On": Market-invested capital intended to provide growth and support long-term spending.
- Assets to "Leave Behind": Legacy assets intended for heirs or philanthropic endeavors.
LIP is the successful synchronization of these buckets. When the $50,000 car purchase is viewed through the lens of LIP, it is no longer an isolated event. It is a modification to the income plan that may require rebalancing accounts, adjusting withdrawal rates, or shifting guaranteed income sources. By treating the purchase as a line item in a broader income stream, the advisor ensures that the ripple does not turn into a tidal wave.
Social Security: The Final Variable in the Ripple Equation
Social Security is the final major piece of the retirement puzzle, and it has the power to either calm the lake or create significant turbulence. It should never be evaluated in a vacuum. Instead, it must be integrated into the existing structure of spending, taxes, and income.
The decision to delay Social Security until age 70 is often mathematically superior on paper, but it is a "theoretical" choice. In practice, the decision to delay must be supported by an "income bridge"—a strategy that provides the necessary cash flow to survive the intervening years without depleting the portfolio prematurely.
Advisors must examine how Social Security interacts with other taxable income. If a client relies on a high-income portfolio, their Social Security benefits may be subject to income tax. Furthermore, if the client is forced to claim early due to poor cash flow management, they suffer a permanent reduction in their lifetime benefits. Therefore, the question is not simply "When should we claim?" but "How do we build an income bridge that makes delaying benefits sustainable?"
Implications for Long-Term Security
The "lake" metaphor provides clients with an intuitive, visual, and memorable way to understand that retirement planning is a dynamic, interconnected process. Every choice is a ripple; every ripple influences the next.
For the advisor, the role is to move beyond mere reactions to market events and toward a proactive, anticipatory model. By modeling the consequences of decisions before they are made, advisors provide more than just investment management—they provide confidence.
When savings, tax strategy, income planning, and Social Security claiming are aligned, the client gains the freedom to spend what they have accumulated with dignity and purpose. They are able to support the people and causes they care about, knowing that their "lake" is deep enough to weather the storms.
In conclusion, retirement success is not the result of a single, brilliant investment choice. It is the result of thousands of small, well-considered decisions, each made with an awareness of the ripples they will create. By mastering these dynamics, Wealthcare Advisors—and others who adopt this holistic methodology—can deliver the clarity and security that every retiree deserves. Retirement is a lifelong journey; by understanding the water, clients can navigate it with confidence.