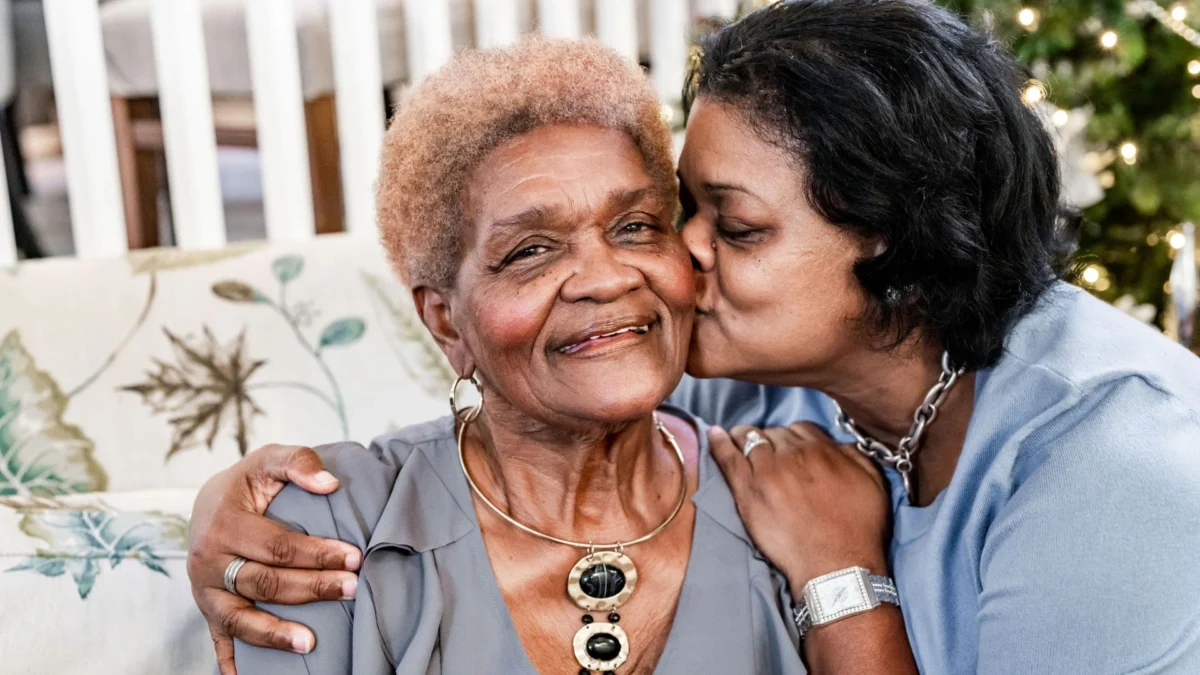
For most of our lives, the hierarchy of the family unit is clear: parents provide the roadmap, the resources, and the guidance. They are the architects of our future. However, as the natural progression of life unfolds, that dynamic undergoes a subtle, often seismic shift. Eventually, the roles reverse, and it becomes the responsibility of adult children to ensure their parents’ futures are as secure as their pasts were.
This transition requires navigating a series of profoundly uncomfortable, yet essential, conversations. We are talking about the "four pillars of legacy and care": financial management, medical autonomy, long-term care preferences, and estate distribution. Addressing these topics before an unexpected health crisis strikes is not merely a matter of convenience; it is a critical act of protection that safeguards both the dignity of the parent and the peace of mind of the family.
The Main Facts: Why Waiting Is a Strategic Error
The most common mistake families make is assuming that "planning for the end" is a conversation reserved for the elderly. Statistics from healthcare providers and estate planners indicate that life-altering events—strokes, sudden accidents, or rapid diagnoses—do not respect age.
When a parent faces a medical emergency without having expressed their wishes, the burden of decision-making falls squarely on the shoulders of their children. Without a roadmap, adult children are forced to guess what their parents might want, often while navigating the emotional trauma of a health crisis. This "decision-making vacuum" is where family conflict, unnecessary legal costs, and profound regret take root.
Chronology of Planning: A Step-by-Step Approach
Successful estate and care planning is not a one-time event; it is an iterative process.
1. The Pre-Conversation Phase
Before you bring up the subject, set the stage. Do not ambush your parents during a holiday dinner or a chaotic family gathering. Schedule a dedicated time to talk. Frame the request in a way that emphasizes partnership rather than control. For example, express that you want to be able to advocate for them effectively should the need ever arise.
2. The Financial Mapping
The initial discussion should focus on financial logistics. Ask: If you were incapacitated tomorrow, who would you trust to manage your accounts? This is the moment to discuss the Durable Power of Attorney (POA). Beyond just the paperwork, discuss the philosophy of their money. What is their approach to debt, risk in investment, and the prioritization of expenses?
3. The Medical Blueprint
Once the financial foundation is understood, move to the medical realm. A medical power of attorney is a legal necessity, but it is useless without a clear understanding of the parent’s values. Discuss their definition of "quality of life." Does this include aggressive life-prolonging measures? What are their feelings regarding Do Not Resuscitate (DNR) orders? These are not just legal questions; they are intimate reflections of a person’s world view.
4. Long-Term Care Strategies
As longevity increases, so does the likelihood of needing long-term care. Discuss the preference between in-home care, assisted living, or memory care facilities. More importantly, discuss the funding of these options. Is there long-term care insurance? Will assets be liquidated to cover these costs?
5. The Final Legacy: Estate Settlement
The final phase of the chronology involves the tangible assets. This is where most family friction occurs. Discussing who gets the house or the sentimental family heirlooms while everyone is healthy can prevent years of litigation and fractured relationships after a parent passes. Ensure that a will or trust is in place and, crucially, that you know where the physical documents are located.
Supporting Data: The Cost of Silence
According to data from the American Association of Retired Persons (AARP), nearly 70% of adults aged 65 and older will require some form of long-term care services in their lifetime. Yet, a significant portion of these individuals have not discussed their care preferences with their children.
The financial implications of this silence are staggering. When a parent enters a facility without a pre-existing plan, families often scramble to access assets, leading to the use of high-interest credit or the liquidation of retirement accounts at unfavorable tax rates. Legal fees for guardianships—which are required if no Power of Attorney exists—can cost thousands of dollars and drag on for months, adding a layer of bureaucratic misery to an already difficult time.
Professional Perspectives and Official Guidance
Legal and financial experts emphasize that the "paperwork" is only 50% of the battle. The other 50% is the communication of intent.
"The goal of an estate plan is not just to transfer wealth; it is to transfer peace," says a leading estate attorney. Financial advisers often point out that clients who involve their adult children in their planning process experience lower levels of anxiety as they age. By inviting children into the conversation, parents are not surrendering their independence; they are creating a support system that ensures their independence is respected for as long as possible.
Furthermore, medical professionals, particularly geriatricians, note that patients who have a documented Advanced Directive receive care that is more aligned with their personal values, leading to higher satisfaction scores and lower rates of traumatic, unwanted interventions in the final stages of life.
The Implications: Changing the Family Dynamic
Initiating these conversations shifts the parent-child relationship from a hierarchical structure to a collaborative one. While this can feel jarring at first—as if you are "parenting your parents"—it is actually the ultimate sign of respect. It acknowledges that your parents are autonomous individuals who have a right to define their own legacy.
Overcoming the "Independence" Barrier
Many parents fear that discussing these topics is a sign that they are losing their agency. To mitigate this:
- Focus on ‘What If’: Frame the conversation around hypothetical scenarios. "If something were to happen, how would you want us to handle it?"
- Lead by Example: Share your own plans. If you are a young professional, mention your own estate plan. It shows that you view this as a standard, responsible adult behavior rather than a "get ready to die" conversation.
- Use Third-Party Mediators: If the emotional barrier is too high, suggest involving a financial planner, an attorney, or even a clergy member. Sometimes, a neutral professional can facilitate the discussion more effectively than a family member.
Conclusion: A Living Process
The most important takeaway is that these plans are not "set and forget." Life is fluid. Financial portfolios change, health statuses fluctuate, and laws regarding estate taxes and medical care evolve.
Families should view these discussions as a "living process"—a yearly or bi-yearly check-in to ensure that the plans on file still match the reality of the parent’s life. By normalizing these discussions, you strip away the fear and replace it with a structured, thoughtful strategy.
In the end, we cannot control the inevitability of aging or the unpredictability of health. However, we can control how we prepare for those realities. The time to start is now, while the sun is still shining, before the shadows of crisis make the path ahead difficult to navigate. By choosing to engage in these hard conversations today, you are giving your parents the greatest gift of all: the assurance that their wishes will be honored, their assets will be protected, and their family will remain united in their memory.
Disclaimer: This article is intended for informational purposes and does not constitute legal or financial advice. For specific planning needs, please consult with a qualified estate attorney or a certified financial planner. You can verify the credentials of financial professionals through the SEC’s Investment Adviser Public Disclosure website or FINRA’s BrokerCheck.