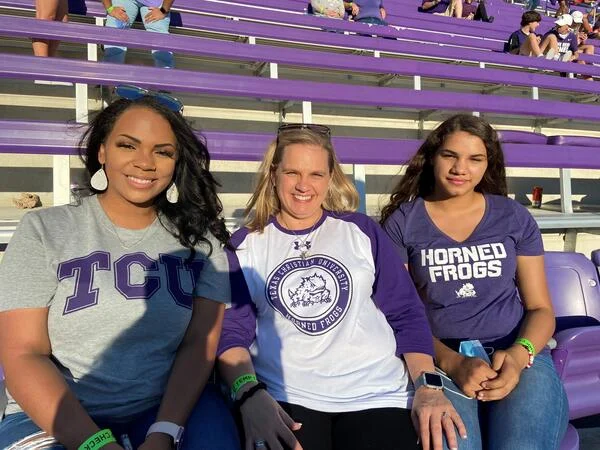
Twelve days before her senior year at Texas Christian University (TCU) was set to begin, Kaylee Webb, a computer information technology major, found herself in the middle of a bureaucratic nightmare. For three years, a $19,000 Parent PLUS Loan had served as the reliable bedrock of her family’s financial planning, covering the essential costs of tuition, fees, and room and board at her dream school. This year, the money never materialized.
"I’d started sending emails to the financial aid office asking why the parent loan wasn’t showing up," Webb recalled. "By August 13, I hadn’t heard anything. So I went to speak with them in person. They were just like, ‘Sorry, you’re not eligible.’"
Webb’s experience is not an anomaly. It is a symptom of a systemic collapse in the implementation of federal financial aid policy, triggered by the "One Big Beautiful Bill Act," which was passed in July 2025. This legislation introduced sweeping caps on previously uncapped Parent and Grad PLUS loans, leaving thousands of students and their families caught in a crossfire of evolving definitions, administrative confusion, and, for many, the sudden threat of being unable to complete their degrees.
A Chronology of Confusion: From Legislation to Litigation
The chaos stems from a disconnect between the Department of Education’s (ED) ambitious policy goals and the practical reality of university administration. When the new loan limits were first proposed, they included legacy provisions intended to protect students who had already begun their academic journeys. Families like the Webbs, who carefully track federal guidance, believed they were safe from the new restrictions.
The situation began to deteriorate in April 2026, when the final rule was released, sparking initial concerns about the complexity of the transition. The crisis reached a boiling point in early August 2026, when the Department of Education issued a "clarification" regarding how legacy access would be calculated.
According to this new guidance, eligibility was no longer determined by the duration of a student’s enrollment, but by the number of completed credit hours. For Kaylee Webb, this proved catastrophic. Half of her credits had been earned through an associate degree program completed while she was still in high school—a strategy she used specifically to get ahead and save money. Because she had surpassed the 120-credit threshold for her degree, the university determined she was no longer protected by the legacy provision.
"We thought we had everything under control with our finances," said Katrina Webb, Kaylee’s mother and a middle-class accountant. "It really feels like someone is stabbing you when you have a child that tried so hard to do all the right things. I’ve talked to other parents, and all their kids brought in transfer credits. These are kids that tried to get ahead, and now they’re being punished."
The Fragmentation of Policy Implementation
One of the most alarming aspects of this crisis is the lack of consistency across higher education institutions. The Department of Education’s guidance, delivered via webinar rather than formal written regulation, has left colleges to interpret the rules on their own.

Loyola Marymount University (LMU) serves as a prime example of this fractured landscape. While some schools have adopted the "credit-hour" calculation, LMU has opted to maintain its commitment to the original written rules, which prioritize years of enrollment over credit hours.
"LMU is aware of the Department of Education’s discussion of a different interpretation during its August webinar and is awaiting formal written guidance from the Office of Federal Student Aid," a university spokesperson stated.
However, this wait-and-see approach has not shielded students from the impact. Kathryn Cook, a student in LMU’s evening law program, found herself in a precarious position. After being told she was "in the clear" regarding the new loan caps, she discovered that the university had been instructed by the Department of Education to use the "full-time program length"—in her case, a shorter three-year J.D. program—to calculate her remaining eligibility. Having already hit the new $257,500 lifetime limit, Cook was left with no further federal loan options.
"It’s becoming really stressful," Cook said. "I have a huge chunk of my budget missing. At this point, I’m struggling to pay my rent. I’m a first-generation student, so my mom doesn’t have the resources to bail me out."
Supporting Data: The Scale of the Disruption
The impact of these changes is far-reaching. At Saint Louis University (SLU), the administrative strain has reached levels comparable to the 2024 FAFSA rollout disaster. Alex DeLonis, assistant vice president of student financial services at SLU, reported that his office received 5,000 calls in a single period—a massive influx of desperate students and parents.
"We thought FAFSA simplification might have been an anomaly, but to have two pieces of legislation that have completely flipped things upside down, and to have to implement them so closely together—it’s just a lot," DeLonis said. "It’s hard to predict and plan when the rules change along the way."
The inability of software vendors to keep pace with the Department’s shifting guidance has forced many financial aid offices to revert to manual, hand-calculated processes. This has led to widespread delays in the disbursement of even the limited funds that remain available. For thousands of students, the result is not just a loss of eligibility, but a state of limbo where tuition remains unpaid, registration is held, and the future remains unwritten.
Official Responses and the "Master Calendar" Dispute
The Department of Education maintains that it has acted within its authority and provided adequate support to institutions. Ellen Keast, an ED spokesperson, argued that the formula for calculating expected time to credential is not new and should not have come as a surprise to schools.

"Not only did the Department implement these regulations on the July 1 statutory timeline, but we published the package two months in advance, providing additional time for schools to prepare," Keast said. Regarding the "credit hour" clarification, she noted that an advisory committee had signed off on the draft in November 2025. "If institutions waited until the final rule was issued to start preparing, that was their decision."
However, industry experts disagree with this assessment. Karen McCarthy, vice president of federal relations at the National Association of Student Financial Aid Administrators (NASFAA), points to the "master calendar" as the primary casualty. Traditionally, the Department finalizes rules by November 1 of the year prior to implementation, allowing colleges time to adjust their systems and communicate with families. By ignoring this timeline, the Department created an environment where confusion was inevitable.
The Human Implication: A Future in Jeopardy
For students like Kaylee Webb, the ordeal concluded with a transition to private loans—a solution that is far from ideal. Unlike federal loans, private loans lack the protections of income-driven repayment and potential loan forgiveness, effectively forcing students to trade long-term financial security for immediate access to their classrooms.
"As a parent, I was trying to keep all the loans that I could out of Kaylee’s name," Katrina Webb noted. "Now, she’s going to have debt that doesn’t have the potential for forgiveness."
For those without the credit history or co-signers required for private financing, the options are even more bleak. Many, like Kathryn Cook, are facing the reality of a leave of absence or the abandonment of their degree programs entirely.
"I feel really kind of abandoned, especially from the lack of communication," Cook said. "It’s just so unjust. I feel like I need to continue telling people how it’s affecting me so they can fix it."
As the higher education sector continues to navigate this volatility, the consensus among observers is that the current model of rapid, reactive policymaking is incompatible with the needs of the student population. Mike Pierce, executive director of the advocacy group Protect Borrowers, summarized the sentiment clearly: "The student loan system and America’s higher education finance system are really not built to handle this kind of change. There is a general sense of anxiety that the rules are shifting faster than the financial aid system can keep up."
Ultimately, while the policy may have been designed to curb the growth of federal debt, the immediate cost is being paid by the students themselves—the very individuals the system was designed to support. As thousands wait for clear, binding, and consistent guidance, the "dream school" experience for many has turned into a desperate fight for survival in a broken financial landscape.