In the complex landscape of personal finance, the most significant obstacles to wealth-building are rarely mathematical. While spreadsheets, interest rates, and investment strategies are the tools of the trade, the true "make-or-break" factor in household financial success is the quality of communication between partners.
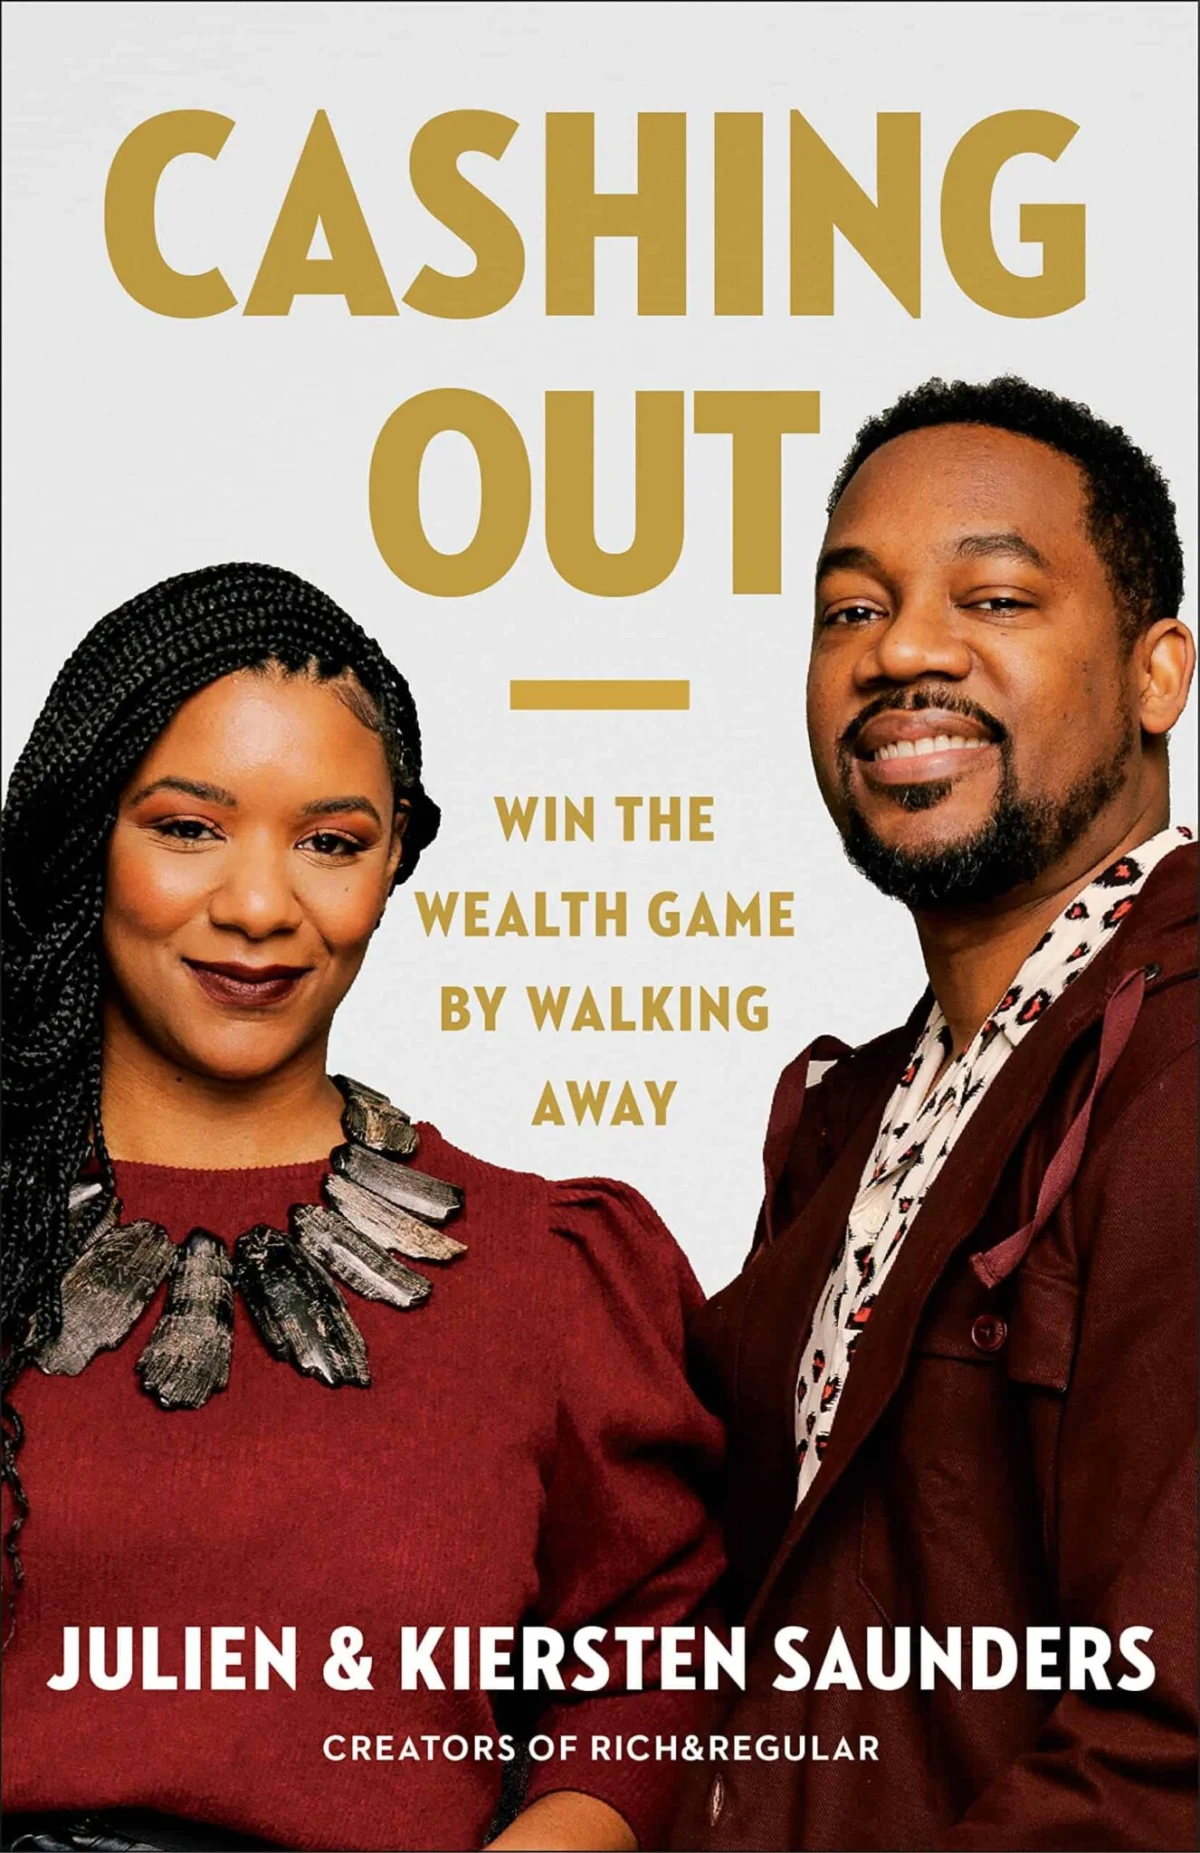
In their latest book, Cashing Out: Win the Wealth Game by Walking Away, financial educators Julien and Kiersten Saunders—the visionaries behind the popular platform rich & REGULAR—argue that when couples fight about money, they are rarely debating the actual currency. Instead, they are caught in a rhythmic, often destructive, behavioral pattern. By reframing these interactions, couples can move from perpetual conflict to a state of collaborative financial prosperity.
The Dance of Dysfunction: Understanding Interaction Patterns
At the heart of the Saunders’ philosophy is the work of clinical psychologist Dr. Sue Johnson, a pioneer in Emotionally Focused Therapy. Dr. Johnson posits that interpersonal conflict is best understood as a "dance." When a couple clashes, it is not the topic (money) or the individuals that are the root cause; it is the rhythm of their interaction.
One partner initiates a move—perhaps an accusatory remark about a credit card bill—and the other responds with a defensive maneuver. This cycle repeats, becoming a rigid, unconscious pattern. To break this, the Saunders suggest that partners must achieve "emotional attunement." If the conflict is the dance, then emotions are the music.
The struggle often arises because partners are listening to different soundtracks. One may be focused on security (the "Barry White" of cautious, deliberate saving), while the other prioritizes spontaneity or lifestyle enjoyment (the "Barry Manilow" of experiential spending). Financial harmony is not achieved by forcing one person to change their song, but by acknowledging that both melodies are playing and finding a way to move in sync.
Chronology of Common Financial Conflicts
Through years of consulting with hundreds of couples, the Saunders have identified a predictable progression of financial friction. These conflicts typically emerge in three distinct, escalating phases:
- The Era of Name-Calling (Spending Conflicts): This is the baseline of domestic friction. One partner acts as the "auditor," tracking boxes on the porch, while the other acts as the "consumer," questioning why the partner needs an entire wardrobe of shoes.
- The Era of Nagging (Saving Conflicts): Once the initial spending arguments reach a stalemate, they evolve into a persistent, low-level hum of irritation. The "saver" begins to police the "spender," creating a dynamic of parent versus child.
- The Era of Blaming (Debt Conflicts): The final, most corrosive stage involves the weaponization of past mistakes. Debt is frequently treated as a moral failing, leading to shame in the borrower and resentment in the non-debt-holding partner.
Supporting Data: Reframing the "Saver vs. Spender" Paradigm
One of the most profound takeaways from Cashing Out is the rejection of the binary labels "saver" and "spender." These labels, while convenient, are intellectually dishonest.
The Saunders argue that saving and spending are not opposing character traits; they are merely functions of a time horizon. A "spender" is simply someone who values the utility of money in the present, while a "saver" is someone who prioritizes the utility of money in the future.
The "Now vs. Later" Framework
When a couple can shift their mindset from "good vs. bad" to "now vs. later," the moral weight of the argument evaporates.
- The Spender’s Reality: They are chasing a specific emotional state—security, pleasure, or spontaneity.
- The Saver’s Reality: They are preparing for a future state of stability.
By identifying the feeling behind the expenditure, couples can bypass the blame game. If one partner spends to feel secure, the other can help find a way to achieve that security without triggering the "irresponsible spender" label.
Official Perspectives on Emotional Attunement
To move past these hurdles, the Saunders offer specific tactical strategies for couples to integrate into their daily financial lives.
From Nagging to Future-Building
Nagging is, by its nature, a defensive trigger. Constant surveillance leads to "conversational quicksand." To escape this, the authors suggest replacing judgmental prompts with "I" statements that invite collaboration.
Instead of asking, "Why are you buying more coffee?", try: "I am really excited about our vacation goal. I am going to cut back on my discretionary spending to help us get there. Would you be willing to join me in that goal?" This pivots the conversation from a critique of the partner to a shared vision of the future. The anticipation of a shared reward acts as a stronger psychological motivator than the restriction of current habits.
Managing the Debt Divide
Debt disparity is a major source of relationship trauma. When one partner carries significant debt, they often feel "wrong" or "bad," while the other feels burdened. The authors emphasize that "shame and obligation" are not the foundations upon which a healthy financial life is built.
Kiersten Saunders shares her own experience, noting that her personal debt once triggered deep defensiveness and a tendency to avoid conflict. True attunement required her to abandon the fantasy of being "rescued" and required Julien to abandon his "judge" persona. They found that combining finances—and treating the debt as a team objective—allowed them to critique the systemic nature of debt rather than each other.
Strategic Implications: The "Tell Me More" Protocol
The most effective tool for any high-pressure conversation, according to the Saunders, is the phrase, "Tell me more."
This phrase serves as a conversational "softener." When a partner expresses frustration, asking them to elaborate creates space for them to be heard, rather than immediately countered. It is a signal of intellectual humility and emotional safety.
However, the authors provide a critical caveat: timing is everything. "Tell me more" is not a tool for an active firestorm. If one partner is in a state of emotional overwhelm—crying, shouting, or retreating—trying to force a constructive, curious conversation will only backfire. In those moments, patience and preservation of the relationship are far more important than solving the budget.
Conclusion: Achieving Collective Harmony
The ultimate goal of financial management in a relationship is not "getting on the same page"—a goal that often implies one person being rewritten by the other. Instead, the goal is harmony.
Harmony allows for individual expression within a collective framework. It acknowledges that two people can have different relationships with time, money, and risk, and still produce a beautiful, synchronized dance. By removing the labels of "spender" and "saver," curbing the habit of nagging, and replacing blame with curiosity, couples can transform their financial life from a source of friction into a testament to their partnership.
As the Saunders conclude in Cashing Out, the wealth game is not won by the person with the most money, but by the couple that has learned how to move together, through every financial season, with mutual respect and unwavering attunement.