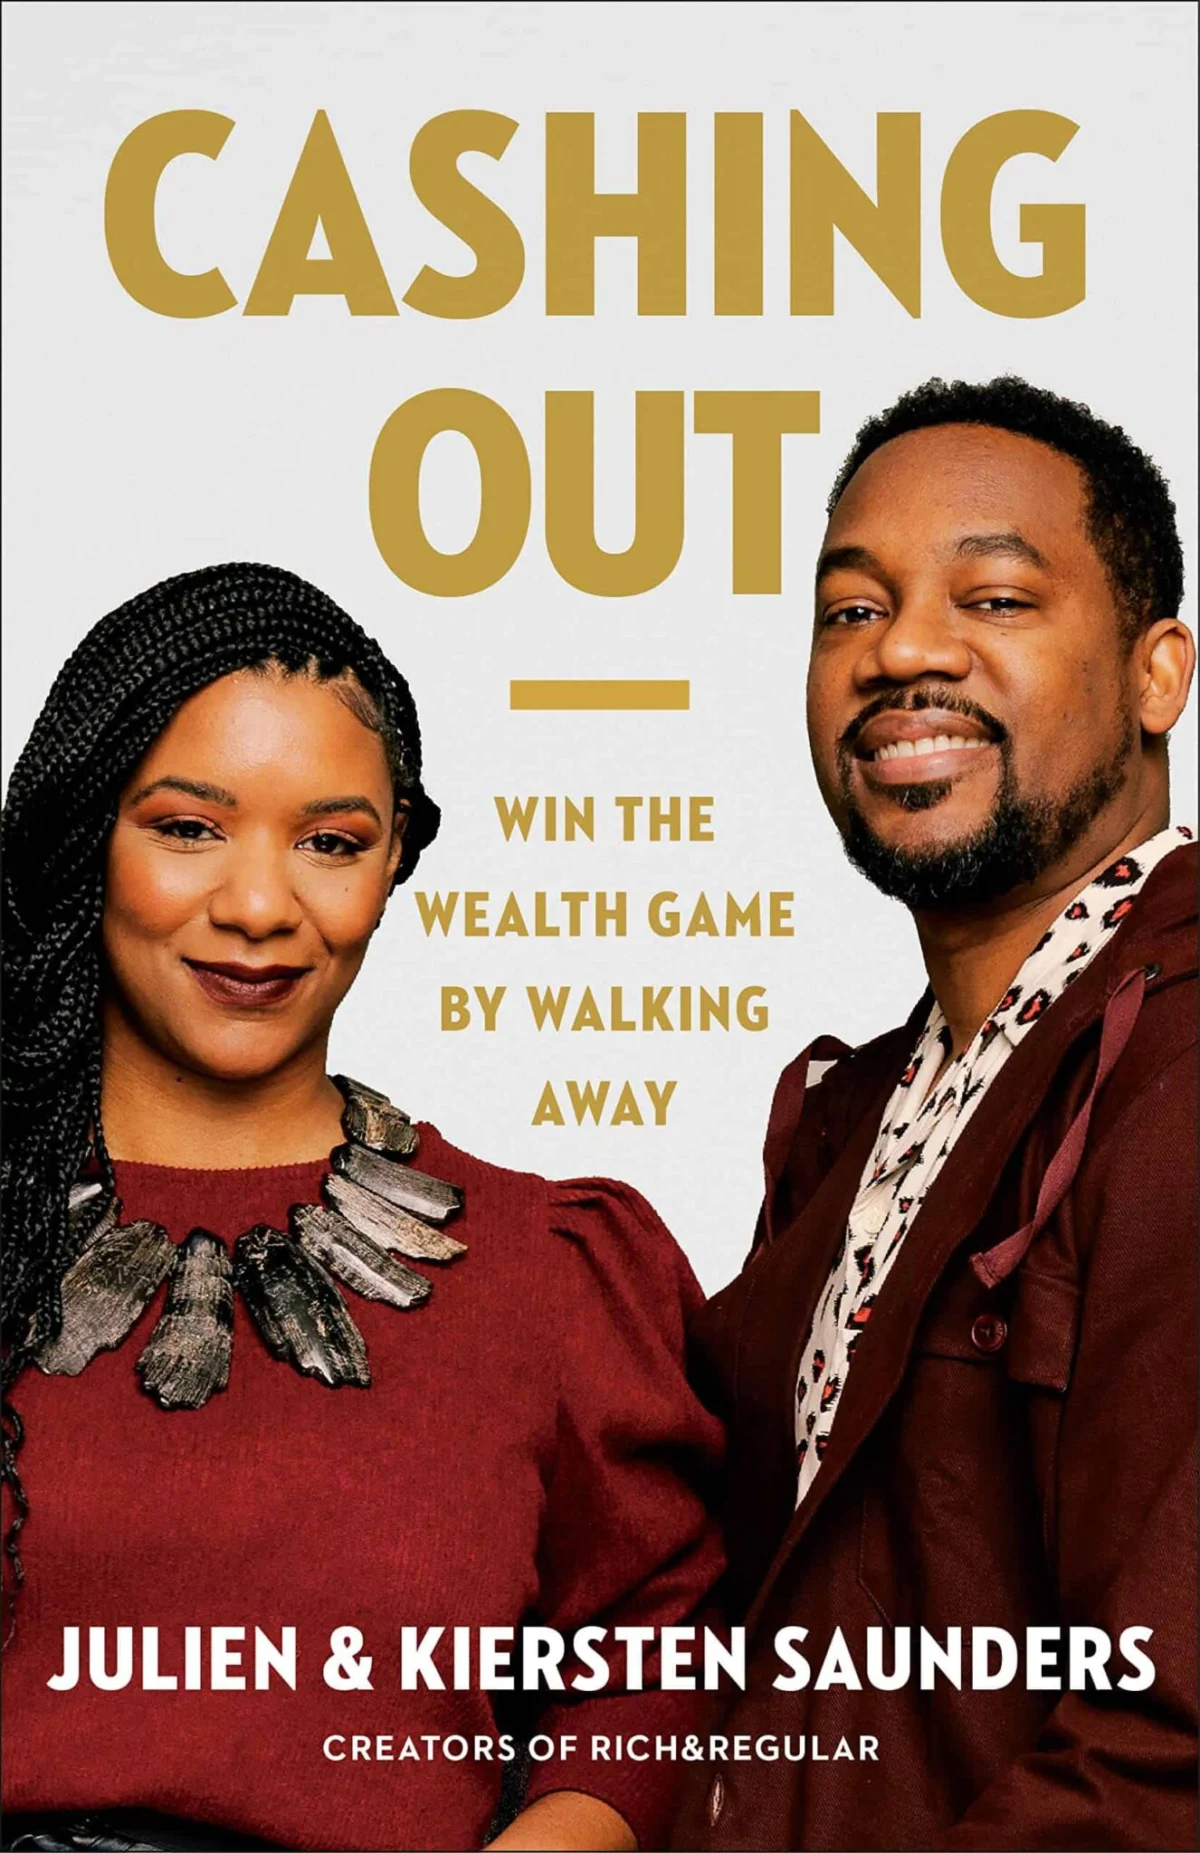
The summer of literature at Get Rich Slowly reaches its grand finale with a compelling excerpt from Cashing Out: Win the Wealth Game by Walking Away. Written by the influential financial duo Julien and Kiersten Saunders—the masterminds behind the rich & REGULAR blog and YouTube platform—this work challenges the conventional, often adversarial, approach to household finances. Published by Portfolio/Penguin, Cashing Out offers a blueprint for couples to navigate the emotional landscape of money management, suggesting that the path to wealth is paved not with spreadsheets alone, but with psychological attunement.
The Core Concept: Financial Conflict as an Emotional Dance
At the heart of the Saunders’ philosophy is the adaptation of Dr. Sue Johnson’s "Emotionally Focused Therapy." Dr. Johnson posits that interpersonal conflict, regardless of the subject matter, is essentially a dance. One partner initiates a movement, and the other responds. Crucially, the problem is not the partners themselves, nor the specific topic of the argument; the problem is the dance—the cyclical, often subconscious, pattern of interaction.
For couples struggling with financial strain, the Saunders argue that the rhythm of these interactions is what defines their relationship. Achieving "emotional attunement" is the key to breaking negative cycles. If conflict is the dance, emotions are the music. If partners are "listening" to different songs—one perhaps operating on a frequency of fear and austerity while the other dances to a tune of instant gratification—they will never find harmony. In many cases, couples are essentially participating in a "silent disco," where both are dancing, but neither can hear the other’s rhythm.
Chronology: From Conflict to Cohesion
The journey toward financial partnership often follows a predictable trajectory, moving from misunderstanding to active conflict, and finally, toward resolution.
- The Recognition Phase: Couples typically reach out for guidance when they feel they have exhausted all avenues of communication. They often arrive at the office of a financial coach or therapist feeling like "frustrated pet owners," seeking someone to explain their partner’s behavior to them because their own attempts have failed.
- The Labeling Trap: The narrative usually begins with the assertion that one partner is a "saver" and the other is a "spender." This binary creates a false dichotomy where the saver is cast as the moral hero and the spender as the reckless villain.
- The Shift in Perspective: The Saunders advocate for a transition from judgment to curiosity. By reclassifying "savers" and "spenders" as simply people with different time horizons—"now" versus "later"—couples can strip away the moral weight of their decisions.
- The Collaborative Dance: Once the labels are removed, the couple begins to view financial goals as a collective project. They stop trying to "fix" one another and start building a shared vision for their financial future.
Deconstructing the Myths of Spending and Saving
The Saunders challenge the widespread belief that spending is inherently bad and saving is inherently good. Instead, they frame spending as a pursuit of a specific emotional state—be it security, spontaneity, or pleasure.
The Fluidity of Financial Labels
The authors emphasize that saving and spending are fluid concepts rather than static personality traits. If a couple saves $20,000 in one year to buy a car, they are "savers" that year. If they spend that same $20,000 the following year to acquire the vehicle, they are "spenders." The only difference is the timeline. By shifting the paradigm from "good or bad" to "now or later," couples can engage in non-judgmental dialogue. The ultimate goal is to find creative, mutually satisfying ways to reach the emotional milestones behind every purchase.
The Dangers of Nagging
Nagging is identified as one of the most destructive behaviors in a financial relationship. Persistent, panicky warnings about saving erode the ability to look at financial situations objectively. When reminders about money are mixed with daily domestic chores, they lose their significance and create a defensive barrier.
The Saunders suggest "reframing" the conversation. Rather than focusing on what is not being bought, couples should obsess over what they are building toward. Using "I" statements—such as, "I am so excited to save for our future trip; would you consider cutting back on coffee so we can reach our goal by November?"—removes the parental tone and replaces it with a partnership model.

Implications for Debt and Emotional Shame
Debt often introduces a layer of shame and resentment that can paralyze a couple’s financial progress. The person carrying the debt may feel inherently "wrong," while the partner without debt may feel burdened by obligation.
The authors note that attempting to reconcile these feelings is like trying to waltz to music that doesn’t match the mood. For the Saunders, the breakthrough occurred when they collectively agreed to drop the "moral failing" narrative surrounding debt. They learned that both frugality and flexibility could coexist. Whether a couple chooses to pay off debt together or maintain separate accounts, the success of the endeavor depends entirely on whether they view the effort as a coordinated dance rather than a unilateral struggle.
The "Tell Me More" Protocol
To foster better communication, the authors propose a simple yet profound linguistic tool: the phrase, "Tell me more."
This phrase serves as a soft invitation for context. It acts as a corrective measure when judgment or harsh language threatens to derail a conversation. A sharp, accusatory remark is like scratching a needle across a record player, halting the music instantly. Conversely, asking for more information encourages the partner to continue expressing their perspective, which is vital for building trust.
However, the authors offer a crucial caveat: the "Tell me more" technique cannot be weaponized. In moments of extreme tension, where one partner feels threatened or intimidated, forced questions will only exacerbate the issue. In these instances, the best approach is patience. Preserving the "dance floor" for a time when both partners feel safe is more important than resolving the conflict immediately.
Conclusion: Achieving Harmony
Ultimately, the goal of managing money as a couple is not merely to "get on the same page," but to achieve a state of harmony. This is a state where each person is allowed to express their financial personality fully, while simultaneously contributing to the collective rhythm of the relationship.
By moving away from the toxic labels of the past and adopting the mindset of a team, couples can transform their financial life from a source of friction into an expression of their shared values. Cashing Out serves as a poignant reminder that while money is the medium of the dance, the relationship is the stage—and keeping that stage safe, open, and communicative is the most profitable investment a couple can make.
For those interested in exploring these concepts further, Julien and Kiersten Saunders’ "Cashing Out: Win the Wealth Game by Walking Away" is available through major retailers. The insights provided in this article have been adapted with permission from the authors and are intended to encourage healthier, more productive dialogues about personal and household finance.