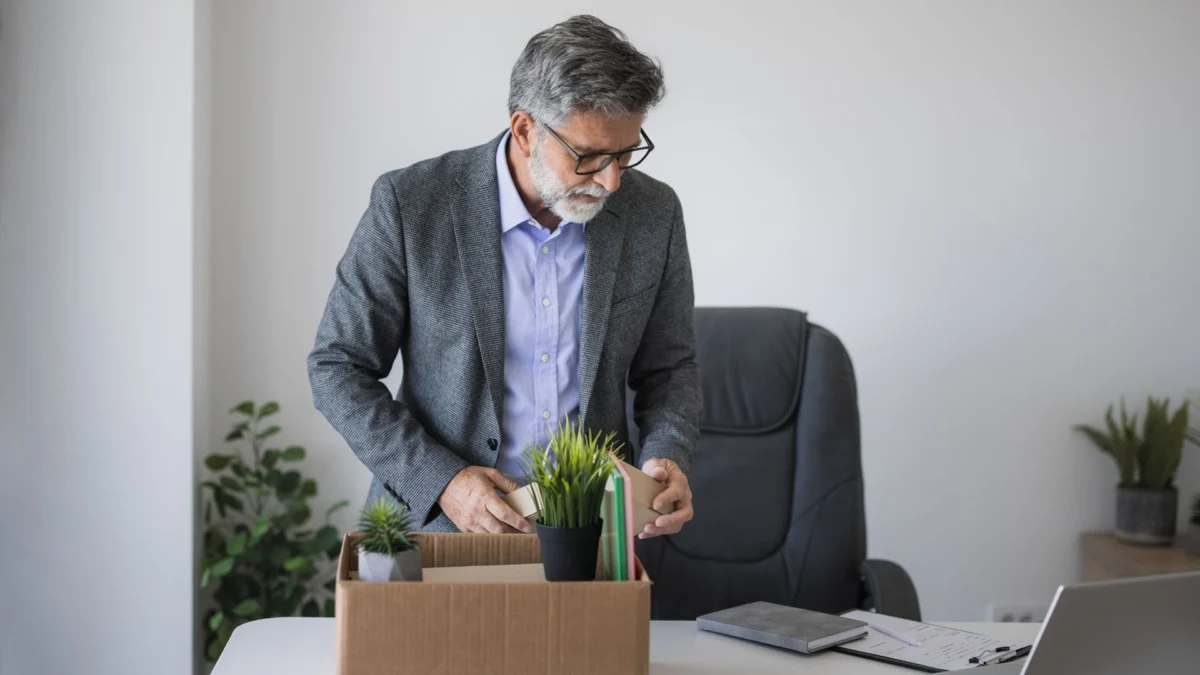
For millions of Americans, the "finish line" of a career is etched in stone: a specific date, a milestone birthday, or a target age like 62, 65, or 70. Retirement planning is fundamentally an exercise in probability, built on the assumption that one will continue to earn a consistent income until that predetermined date. However, the reality of the modern labor market is often far less predictable. When a career ends prematurely—whether due to corporate restructuring, sector-wide downturns, or sudden health challenges—the retirement strategy built over decades can unravel in an instant.
As the economic landscape shifts, the vulnerability of older workers is moving to the forefront of financial discourse. Protecting one’s golden years requires moving beyond simple savings goals and toward a model of aggressive, flexible resilience.
The Economic Backdrop: A Fragile Labor Market
The current state of the U.S. economy presents a paradox for workers in their 50s and 60s. While macroeconomic indicators often point to resilience, granular data tells a more complicated story. According to the August 2026 jobs report, while the national unemployment rate held steady at 4.1%, the information sector saw a contraction, shedding 23,000 jobs.
This trend is mirrored in the private sector. The ADP National Employment Report indicated that private payroll growth slowed to 38,000 in August, falling short of the 47,000 jobs economists had projected and trailing behind the 46,000 added in July. For a professional in their peak earning years, these figures are not just statistics; they are warning signs. When industries contract, the cost of re-entry for older workers—who often command higher salaries—can be prohibitive, leading to longer periods of unemployment that directly erode retirement nest eggs.
Chronology of a Financial Disruption
The path to an unexpected early retirement often follows a predictable, yet devastating, sequence:
- The Trigger: A sudden layoff or the necessity to leave a position due to industry consolidation or burnout.
- The "Bridge" Phase: Initial optimism about a quick job search gives way to the reality of an age-biased labor market. During this time, the individual begins burning through liquid savings to maintain their standard of living.
- The Healthcare Gap: If the individual has not yet reached the age of 65, the loss of employer-sponsored health insurance creates a massive financial liability. Relying on COBRA or private market alternatives can cost thousands of dollars per month, further draining assets.
- The Panic Pivot: Faced with mounting costs, the individual is often forced to make irreversible decisions: accessing 401(k) funds early, incurring tax penalties, or claiming Social Security benefits at a reduced rate.
- The Long-Term Impact: The compounding effect of missing out on peak-earning years and the premature depletion of retirement accounts results in a significantly lower standard of living for the remainder of their life.
Supporting Data and the Cost of Inaction
The financial consequences of early, forced retirement are profound. According to various personal finance studies, the "sequence of returns risk"—the risk of experiencing poor investment returns or needing to withdraw funds during a market downturn—is the single greatest threat to a retiree’s portfolio.
When an individual is forced to sell assets during a period of market volatility to cover living expenses, they "lock in" losses. This prevents the portfolio from participating in the eventual market recovery, permanently reducing the principal balance. Furthermore, claiming Social Security before reaching full retirement age results in a permanent reduction of monthly benefits. For a retiree who might live into their late 80s or 90s, this cumulative loss can amount to hundreds of thousands of dollars in lifetime income.
Strategies for Resilience: A Proactive Approach
1. Stress-Test Your Retirement Plan
Financial planning is not a "set it and forget it" process. To be truly prepared, you must run your current financial model through "stress tests." Ask yourself:
- "If I lost my income today, how many months could I survive without touching my 401(k)?"
- "What is my ‘Plan B’ if I am forced to retire three years earlier than expected?"
- "Have I accounted for the cost of private health insurance until I hit Medicare eligibility?"
By modeling these scenarios, you can identify the gaps in your defense. If the math doesn’t work, you have time to adjust your savings rate or rebalance your portfolio to be more conservative.
2. Get Your Financial House in Order
Preparation begins with a clear audit of your cash flow. Distinguish between essential fixed expenses and discretionary spending. In the event of a job loss, the goal is to survive as long as possible on cash reserves rather than dipping into retirement accounts.
Financial professionals frequently suggest a three-to-six-month emergency fund, but for those in their 50s and 60s, that may be insufficient. Aiming for a 12-month reserve—held in high-yield savings or money market funds—provides a vital buffer that allows you to be selective in your job search rather than desperate.
3. Healthcare Planning: The Hidden Liability
Healthcare is often the most overlooked line item in retirement planning. For those who lose their job before age 65, the transition to COBRA is often the first step, but it is rarely the most efficient. Explore options via the Affordable Care Act (ACA) marketplace, which may provide subsidized coverage depending on your income level. Understanding the nuances of Medicare—specifically the difference between Parts A, B, C, and D—is essential for those approaching the 65-year mark. Do not wait until you are unemployed to investigate these options.
4. Stay Connected and Relevant
The "hidden" job market is where most senior-level opportunities are filled. Maintaining a robust professional network, keeping licenses active, and pursuing certifications in new technologies are not just career-building tasks—they are risk-mitigation strategies. If you are forced out of a role, a strong network can be the difference between a three-month job search and a two-year retirement gap.
Implications for the Future
The traditional model of a linear career—climbing the ladder until a scheduled exit—is becoming a relic of the past. The future of retirement planning is "nonlinear." It involves the possibility of career pivots, extended periods of "unretirement," and the need for greater liquidity.
The implications for the individual are clear: we must stop viewing retirement as a fixed destination and start viewing it as a flexible state of being. By building financial buffers, securing healthcare contingencies, and maintaining professional agility, workers can protect themselves against the volatility of the labor market.
A Final Note on Professional Guidance
While the strategies outlined here provide a framework, individual circumstances vary wildly. It is highly recommended that you consult with a certified financial planner or a fiduciary adviser who can provide personalized analysis of your portfolio and tax situation. When choosing an adviser, always verify their credentials through the SEC’s AdviserInfo database or FINRA’s BrokerCheck.
The goal of your retirement plan should not just be to maximize growth, but to ensure that even when the unexpected happens, your vision for the future remains intact. Don’t wait for a pink slip to start your stress test; the best time to protect your retirement was yesterday, but the second best time is today.