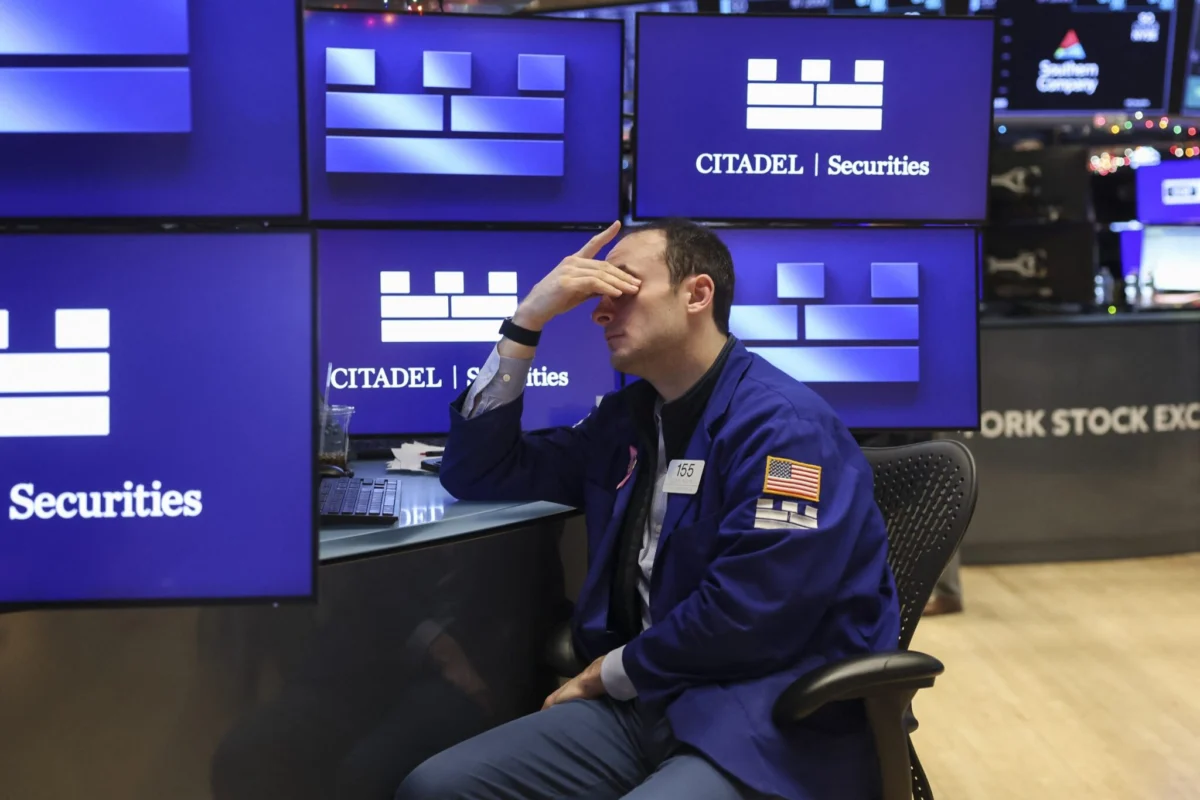
The financial world is currently navigating a period of unprecedented technological optimism, driven by the rapid integration of artificial intelligence (AI) across global industries. However, a growing chorus of market analysts is sounding the alarm, suggesting that the current bull run—while still possessing momentum for the short term—is tracking the classic trajectory of a "late-stage bubble."
According to recent reports from prominent financial institutions and economists, investors should prepare for a peak in late 2026, followed by a significant and potentially painful correction in 2027. This analysis explores the mechanics of this projected "bust," the data supporting these bearish forecasts, and the structural risks currently hidden beneath the surface of the S&P 500’s record-breaking performance.
Main Facts: The S&P 500’s "Blow-Off" Rally and Subsequent Collapse
The central thesis of the current market outlook is a bifurcated timeline: a final "blow-off" rally followed by a sharp deleveraging. James Reilly, a senior markets economist at Capital Economics, has reiterated a bold forecast that encapsulates this sentiment. Reilly predicts that the S&P 500 will continue its ascent, reaching a peak of 8,250 by the end of 2026. This would represent a roughly 7.7% increase from current levels, fueled by continued AI hype and corporate investment.
However, the "hangover" is expected to be severe. Capital Economics projects that by the end of 2027, the index will plunge by approximately 21%, settling at 6,500. This correction would effectively erase two years of gains, driven by the exhaustion of AI-related capital expenditures and a tightening of financial conditions.
The primary driver of this volatility is the "AI bubble" narrative. Analysts argue that while the transformative power of AI is real, the market’s valuation of that power has decoupled from the underlying fiscal realities. Much like the Dotcom era of the late 1990s, the current market is characterized by extreme concentration, soaring price-to-earnings (P/E) ratios, and a "fear of missing out" (FOMO) that has driven equity issuance to levels historically associated with market peaks.
Chronology: The Trajectory of a Bubble (2023–2027)
To understand the projected 2027 crash, one must look at the chronological development of the AI-led market cycle:
- The Genesis (2023–2024): The launch of generative AI tools sparked a massive reallocation of capital. The "Magnificent Seven" tech giants led the charge, with their market capitalizations swelling as they pivoted their entire business models toward AI infrastructure.
- The Acceleration Phase (2025): AI integration moves beyond the "hyperscalers" (Microsoft, Alphabet, Amazon) and into broader enterprise software and manufacturing. This phase is expected to see a surge in IPOs and follow-on equity offerings as companies scramble to fund AI R&D.
- The Blow-Off Rally (2026): According to Reilly’s forecast, 2026 will be the "final stage" of the bubble. During this period, stock valuations are expected to reach their zenith, with the S&P 500 hitting the 8,250 mark. This period is often characterized by high volatility and a final, frantic push by retail and institutional investors to enter the market.
- The Inflection Point (Early 2027): The "AI hyperscalers"—the massive cloud and data providers—are projected to see their combined free cash flow turn negative. This occurs as the massive capital expenditures (CapEx) required to build AI data centers fail to produce immediate, proportional revenue.
- The Correction (Late 2027): As earnings growth fails to meet the sky-high expectations baked into 2026 prices, a mass sell-off begins. The 21% drop to 6,500 reflects a return to fundamental valuation metrics and a "normalization" of the AI sector.
Supporting Data: Five Indicators of an Imminent Bust
James Reilly and other analysts point to five specific data points that suggest the market is currently in a "late-stage bubble."
1. Extreme Valuations and the CAPE Ratio
The cyclically adjusted price-to-earnings (CAPE) ratio, which smoothes out earnings over a ten-year period to account for economic cycles, is currently approaching levels last seen during the height of the Dotcom bubble in 2000. Furthermore, when comparing S&P 500 valuations to Treasury bond yields, the equity risk premium has shrunk to a level that suggests stocks are significantly overvalued relative to "risk-free" assets.
2. Unsustainable Earnings Growth Expectations
Forward-looking earnings-per-share (EPS) growth for the S&P 500 is currently modeled on a trajectory that mirrors the unsustainable peaks of the late 1990s. Market participants are pricing in a level of perpetual growth that historically has never been maintained over a long-term horizon, particularly in the face of rising interest rates.
3. The Hyperscaler Cash Flow Crisis
AI requires immense physical infrastructure—GPUs, data centers, and massive amounts of electricity. The "hyperscalers" (Amazon, Google, Microsoft, and Meta) have committed hundreds of billions of dollars to this build-out. However, data suggests that the combined free cash flow for these entities is expected to turn negative by 2027. If the "AI payoff" in terms of consumer and enterprise spending does not materialize rapidly enough to offset these costs, the financial foundation of the rally will crumble.
4. Market Concentration and Narrowness
The current rally is notoriously "narrow," meaning a very small number of stocks are responsible for the majority of the index’s gains. Historically, when the top five or ten stocks in the S&P 500 account for an outsized portion of the total market cap, the market becomes fragile. A downturn in just two or three of these "pillars" can trigger a systemic collapse.
5. Booming Equity Issuance
A surge in Initial Public Offerings (IPOs) and follow-on offerings is a classic sign of a bubble’s end. Companies rush to issue new stock when they believe prices are at their peak to raise maximum capital. Reilly notes that the current pipeline of equity issuance suggests that the end of the cycle is "months away, not years," indicating that the 2026/2027 timeline is rapidly approaching.
Official Responses and Expert Perspectives: The Yield Factor
While Reilly focuses on internal market metrics, Ruchir Sharma, Chairman of Rockefeller International, points to external macroeconomic pressures—specifically the bond market.
The 5% Threshold
In a recent analysis for the Financial Times, Sharma warned that the AI bubble is inextricably linked to the 10-year Treasury yield. As of late 2024, the 10-year yield reached 4.97%. Sharma argues that if the yield "decisively breaches" the 5% mark, the era of "easy money" that fueled the AI boom will officially end.
A yield above 5% makes borrowing for massive AI projects significantly more expensive. Furthermore, it creates a "headwind" for stocks, as investors can find attractive, low-risk returns in bonds, reducing the incentive to hold volatile tech equities.
The Debt Burden
Sharma also highlights a critical difference between the current era and the Dotcom era: the national debt. During the 1990s, the U.S. debt-to-GDP ratio was significantly lower. Today, it exceeds 100%. "Rising public borrowing costs will squeeze other borrowers sooner and hit the bubbly AI markets harder," Sharma noted. In this environment, the government’s cost to service its debt competes directly with the private sector’s ability to fund innovation.
The Shift in Sentiment: Ed Yardeni
Even long-term market optimists are beginning to hedge their bets. Ed Yardeni, the veteran economist who coined the term "Bond Vigilantes" and has been a proponent of a "Roaring 2020s" scenario, recently adjusted his outlook. Yardeni lowered the probability of a continued bullish decade from 80% to 70%, while raising the odds of a bearish outcome to 30%. He cited "unnerving" developments in the oil and bond markets as the primary reasons for his increased caution.
Implications: What a 2027 Correction Means for the Global Economy
The transition from an AI-led boom to a 2027 bust would have far-reaching consequences beyond the stock tickers of Wall Street.
1. A Re-evaluation of the AI Value Proposition
A 21% market correction would likely lead to a "Rationalization Phase" for artificial intelligence. Companies will be forced to move beyond the experimental phase and demonstrate clear Return on Investment (ROI). Many AI startups that rely on cheap venture capital and high stock valuations may face insolvency or forced acquisitions.
2. Tightening of Corporate Credit
If Treasury yields remain high and stock prices fall, the cost of capital will skyrocket. This will disproportionately affect tech companies that rely on debt or equity issuance to fund their research and development. We may see a significant slowdown in the pace of technological advancement as companies prioritize cash preservation over speculative innovation.
3. The Wealth Effect and Consumer Spending
A 21% drop in the S&P 500 would represent trillions of dollars in lost household wealth. This "negative wealth effect" often leads to a sharp contraction in consumer spending, which could push the broader U.S. economy into a recession in 2027 or 2028.
4. Fiscal Pressure on the U.S. Government
As Sharma pointed out, if interest rates stay high while the economy slows down, the cost of servicing the U.S. national debt becomes a primary economic drag. The government may be forced to choose between austerity measures (cutting spending) or further borrowing, both of which carry significant political and economic risks.
Conclusion
The consensus among these analysts is not that AI is a "fraud," but rather that the financial markets have "over-promised and over-priced" its immediate impact. The predicted 8,250 peak in 2026 represents the final gasp of speculative euphoria. For investors, the message is clear: enjoy the gains of the coming months, but remain vigilant. The transition from 2026 to 2027 may mark the end of the "Roaring 2020s" and the beginning of a more sober, debt-constrained economic reality.