
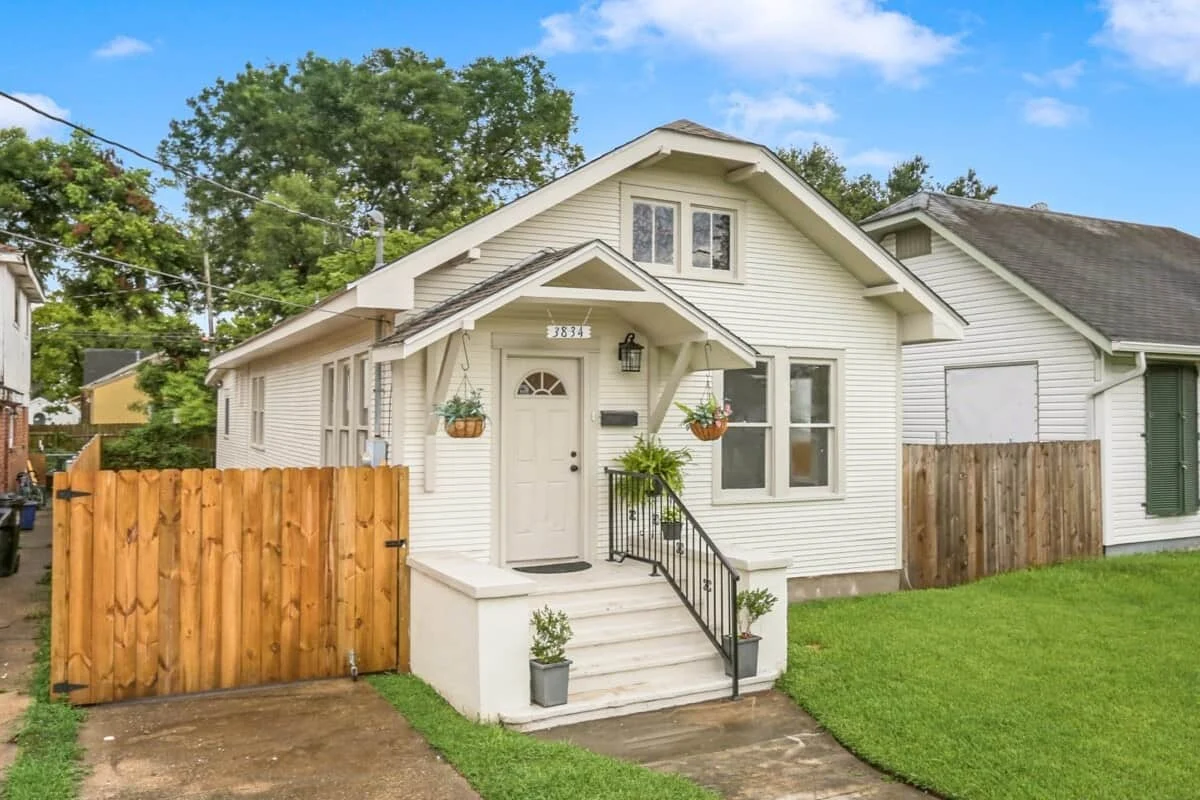
In the current real estate landscape, characterized by a complex interplay of high interest rates and fluctuating inventory, many homeowners are reconsidering their assets. For those who aren’t quite ready to sell but are looking for a way to offset rising ownership costs, renting out a property has emerged as a premier financial strategy. Whether you are looking to rent out a spare room or convert an entire primary residence into an income-generating investment, the transition from homeowner to landlord requires more than just finding a tenant—it requires a fundamental shift in mindset from resident to business owner.
The Financial and Strategic Landscape
Renting out your home offers a unique path to long-term wealth, allowing you to retain the benefits of property appreciation while generating monthly cash flow. However, the decision to become a landlord should be treated as a serious business venture. With more sellers currently active in the market than buyers, and with renting remaining a more cost-effective choice for many families, the demand for quality rentals is high. Yet, this opportunity comes with significant legal, financial, and operational responsibilities.
Key Considerations for Prospective Landlords
- Income Generation: The potential to cover your mortgage, taxes, and insurance through rental income.
- Asset Preservation: Retaining ownership of an asset that may appreciate over time.
- Operational Risk: The reality of vacancies, maintenance emergencies, and the complexities of tenant management.
1. Regulatory Compliance: The Legal Foundation
Before you list your home, you must navigate a maze of legal requirements. Failing to do so can result in hefty fines, legal disputes, or the forced termination of your rental plans.
Understanding HOA and Municipal Constraints
If your property is part of a Homeowners Association (HOA) or a condominium board, you are subject to their governing documents. "The fines for breaking HOA or condo association rules land on you, not your tenant," explains Doug McLain, owner of Dynamite Management. "You’re also still on the hook for assessments or any damage your tenant causes to the common areas."
Beyond the HOA, you must verify local zoning laws and rental ordinances. Some municipalities require a "Certificate of Rental Compliance" or a specific landlord permit. Skipping this step can invalidate your insurance or lead to immediate legal trouble.
2. Defining Your Rental Strategy
The "best" rental strategy is not universal; it is highly dependent on your goals, your location, and your property type.
Long-Term vs. Short-Term Rentals
- Long-Term Rentals: Typically involve 12-month leases. These offer stability, predictable income, and lower turnover costs.
- Short-Term/Mid-Term Rentals: Often found on platforms like Airbnb or VRBO. While they can command significantly higher premiums, they require a hospitality-focused approach. "Owners often default to long-term renting without asking whether it’s the best return on their investment," notes the team at Evolve, a vacation rental management company. "In many markets, short- and mid-term stays can earn much more than traditional 12-month leases."
3. Financial Planning: Beyond the Monthly Rent
One of the most common pitfalls for new landlords is failing to account for the "hidden" costs of property ownership.
The Mathematics of Profitability
Many homeowners look at their mortgage payment and subtract it from the expected rent, assuming the difference is profit. This is a dangerous simplification. You must factor in:
- Vacancy Reserves: Even the best rentals experience periods of vacancy.
- Maintenance Funds: Plan for recurring costs (landscaping, HVAC servicing) and capital expenditures (roofing, water heaters).
- The 50% Rule: A standard industry benchmark, this rule suggests that you should expect to spend roughly 50% of your gross rental income on operating expenses (excluding the mortgage).
"First-time landlords often over-estimate the amount of rent they will receive and under-estimate the amount of time it will take to start earning income," cautions Hal Wilkerson of Hawaii Coastal Property Management. "Some markets are seeing compression on rents, which can translate to a property sitting longer than a landlord may expect."
4. Operational Management: DIY or Hire a Pro?
Deciding whether to manage the property yourself or hire a professional is a pivotal choice.
When Self-Management is Viable
Self-management can save you 8% to 12% of your monthly rent in management fees. It is feasible if you live within a short distance of the property, possess basic DIY repair skills, and are prepared to handle 2 a.m. phone calls regarding broken pipes. "Owning and managing homes can be an excellent way to build wealth," says Tony Jacobsen, president of Landlords of Iowa. "However, it is essential to educate yourself on state landlord-tenant laws and fair housing guidelines."
The Case for Professional Property Management
If you live out of state or simply lack the bandwidth to deal with tenant disputes and maintenance, a property manager is an invaluable asset. They handle the heavy lifting: tenant screening, rent collection, legal compliance, and vendor coordination. For many, the peace of mind is worth the management fee.
5. Risk Mitigation: Insurance and Legal Protections
Your standard homeowner’s insurance policy is likely insufficient for a rental property. You need a landlord policy that specifically covers liability for the tenant, loss of rental income in the event of a disaster, and potential property damage.
Furthermore, you must have a rock-solid lease agreement. As attorney Michael Denha of Southfield, MI, urges: "Landlords should use a clear and comprehensive lease, document the property’s condition prior to move-in, and have the tenant sign a move-in checklist. Taking these steps up front can prevent disputes, costly problems, or litigation."
6. Tenant Screening: The Critical Filter
Your property is your biggest asset; the person you allow to live in it will either protect that asset or deplete it. A consistent screening process is mandatory.
Best Practices for Screening
- Standardize Everything: Apply the same criteria—income-to-rent ratios, credit score thresholds, and background check requirements—to every single applicant to ensure compliance with the Fair Housing Act.
- Verify, Don’t Just Trust: Call previous landlords, verify employment, and check references.
- Adverse Action: If you deny an applicant based on a credit report, you are legally required to provide them with an "adverse action notice" under the Fair Credit Reporting Act.
7. The Mechanics of Daily Operations
Once the tenant has moved in, the nature of your relationship changes. You are no longer just a homeowner; you are a service provider.
Maintaining the Property
Regular maintenance is not just about keeping the tenant happy—it is about protecting your investment. Proactive maintenance prevents minor leaks from turning into massive water damage claims. Establish a clear protocol for how maintenance requests are submitted, handled, and tracked.
Communication and Rent Collection
Use modern, automated systems for rent collection to avoid the "check is in the mail" excuses. Online portals are not only convenient for tenants but also provide a paper trail that is essential for accounting and tax purposes.
8. Navigating the Eviction Process
While it is the scenario every landlord dreads, you must have a plan for non-payment or lease violations. Eviction is a strictly regulated legal process. Never attempt "self-help" evictions, such as changing the locks or shutting off utilities—these actions are illegal in almost every jurisdiction and can lead to severe lawsuits against you. Always consult with a local attorney who specializes in landlord-tenant law before initiating any legal action.
Summary: Is Landlording Right for You?
Renting out your house is a powerful financial tool that can diversify your income and build equity. However, it requires a commitment to ongoing education, strict adherence to legal standards, and the emotional resilience to handle the challenges of property management.
Before listing your home, perform a rigorous audit of your finances, consult with a tax professional regarding rental income reporting, and conduct a thorough analysis of your local market. If you are prepared to treat the property as a business, you will find that the rewards—both financial and strategic—can be substantial. If you are not prepared for the responsibilities, consider whether selling the property or utilizing a full-service property management firm is a more sustainable path forward.